The question
Every calculator gives a monthly payment. None says what to do with the savings.
A buyer with savings has one real decision: how much of them to put down, and how much to leave invested. Bank calculators work out the monthly payment for a given loan. They do not compare the two uses of the same euro.
Hypocheck does. It prices the closing costs, checks the cash actually covers them, and then sets the interest a larger down payment saves against what the same money would earn in the market over the life of the loan.
How it reads
Styled as a receipt, read from top to bottom
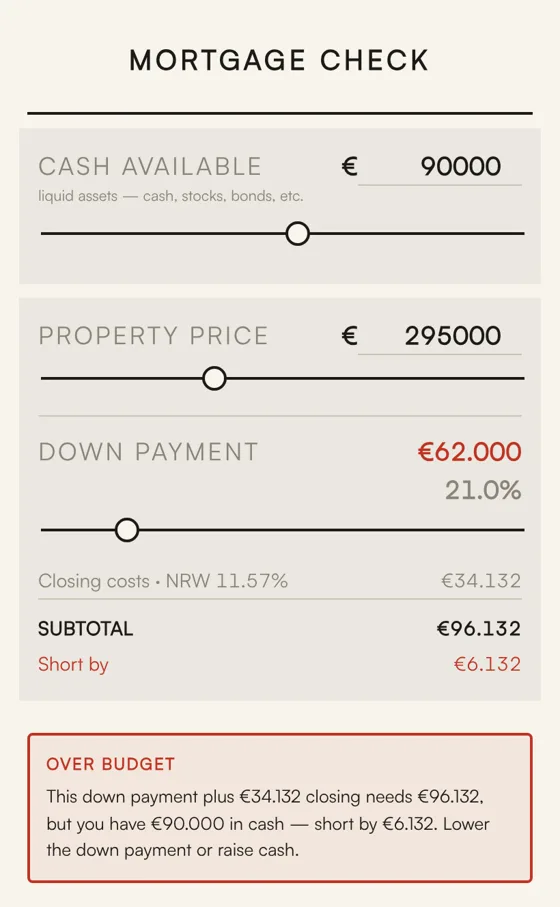
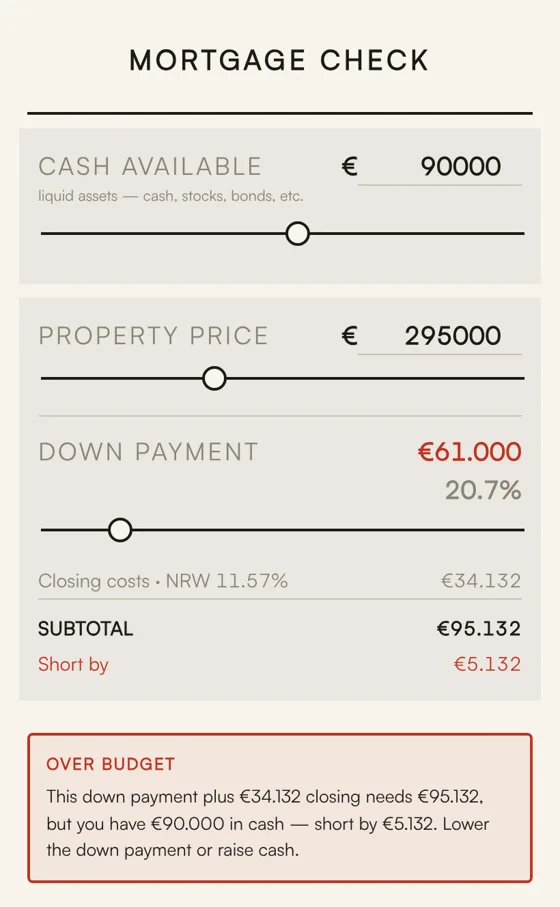
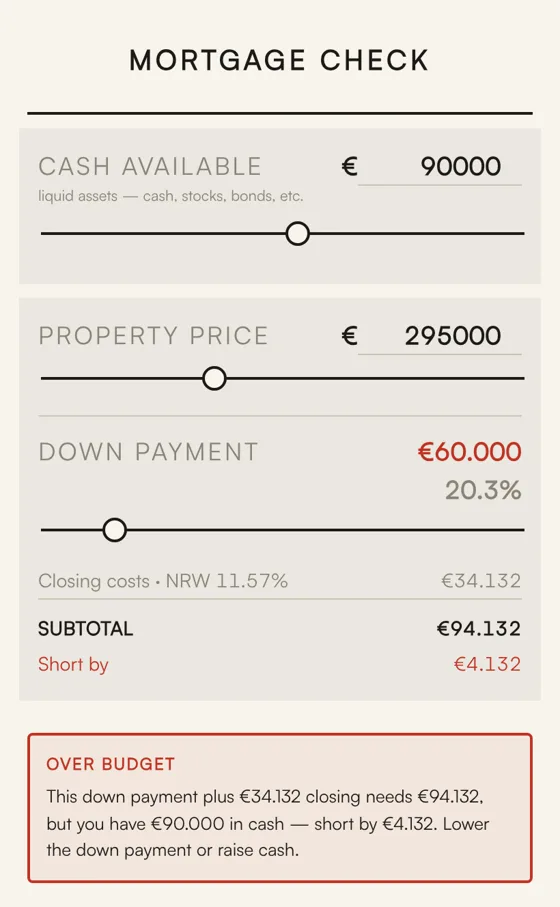
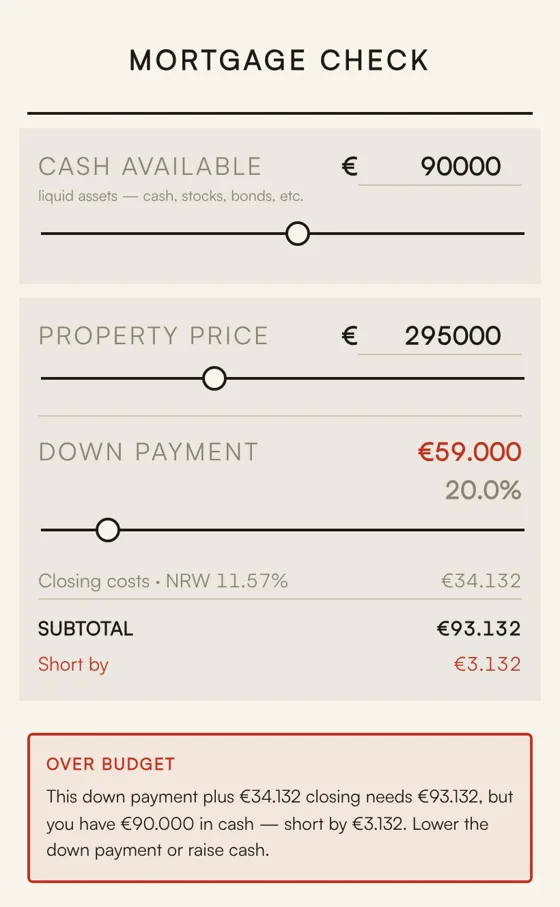
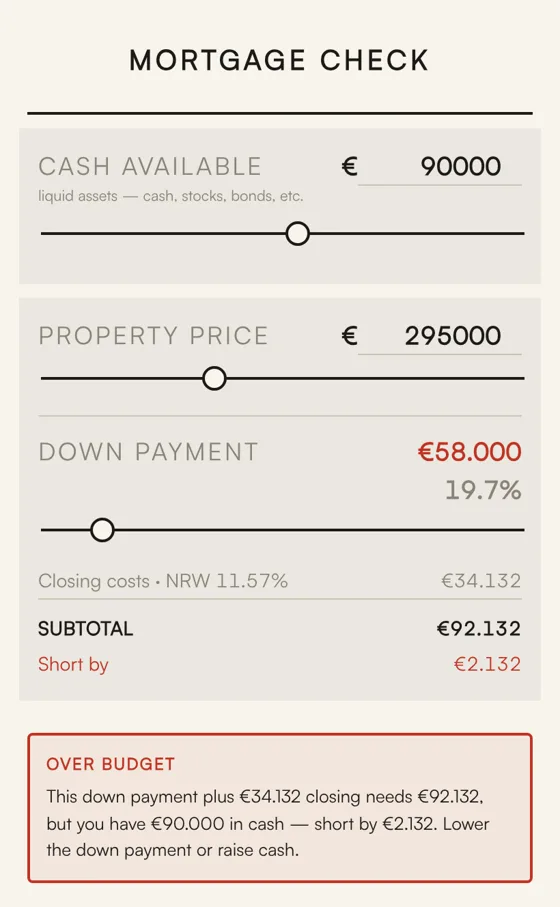
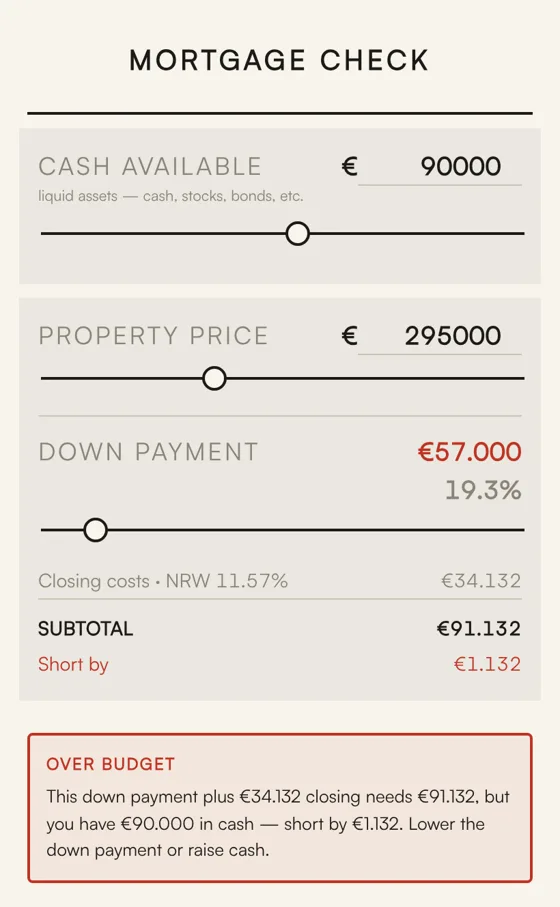
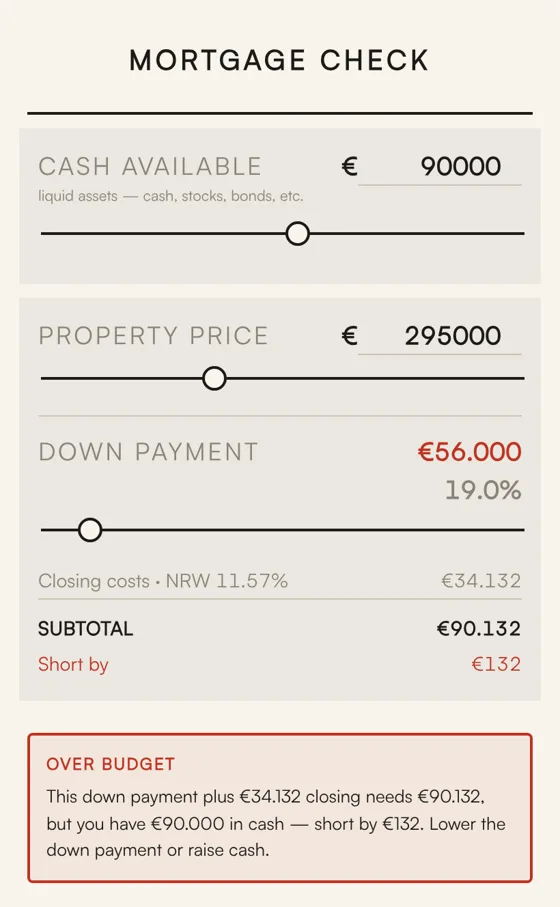
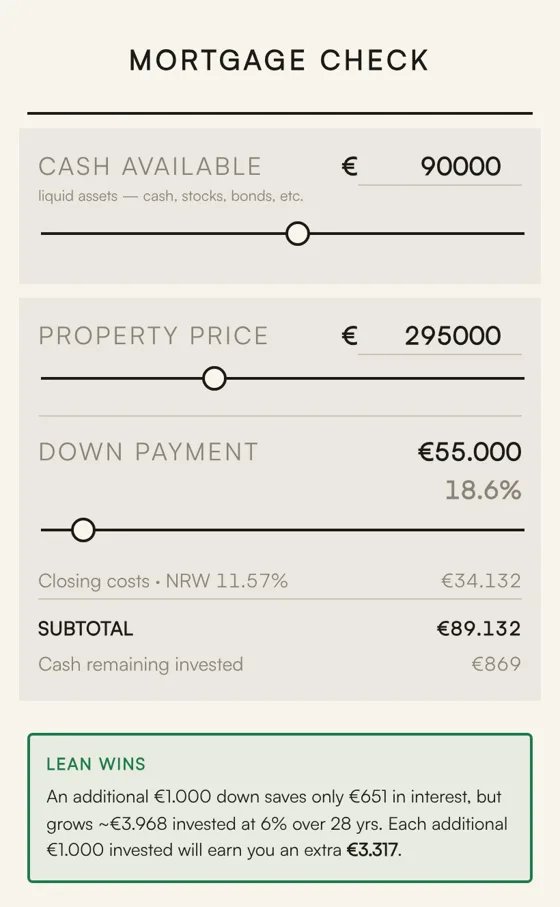
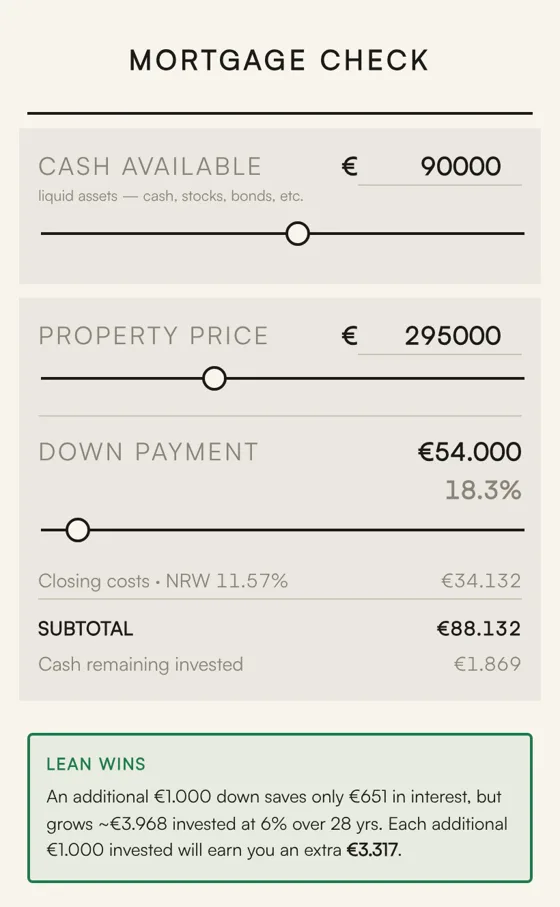
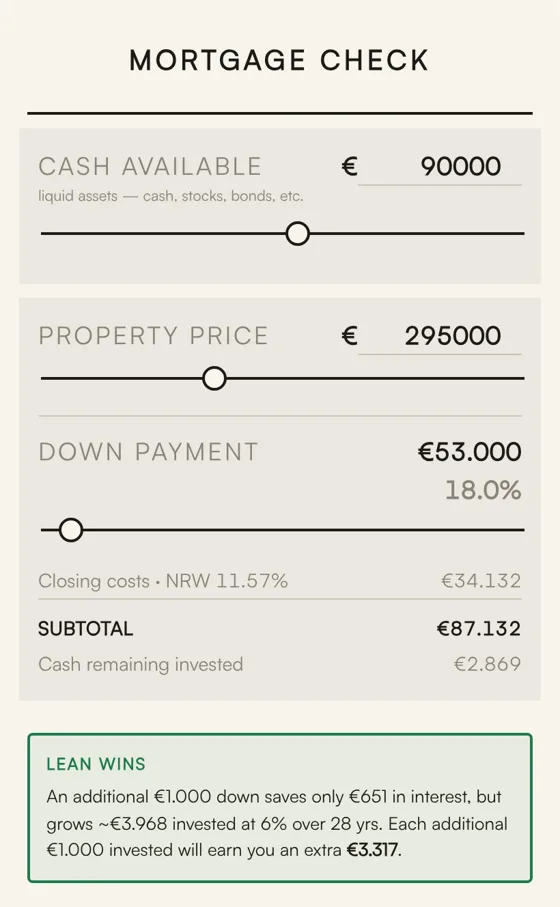
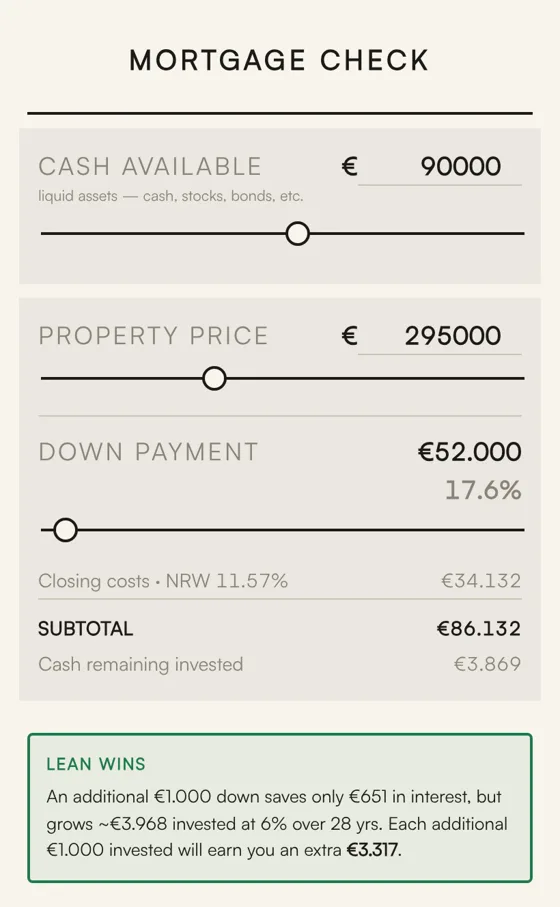
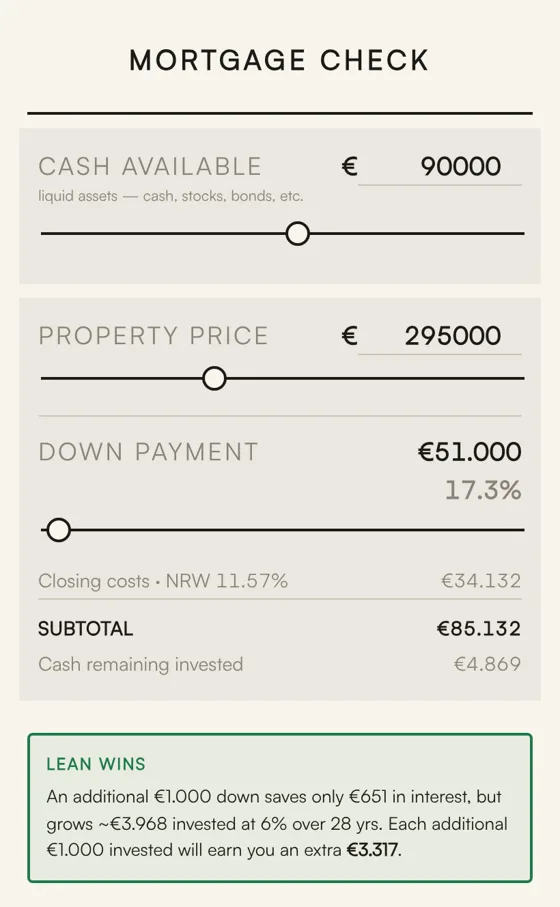
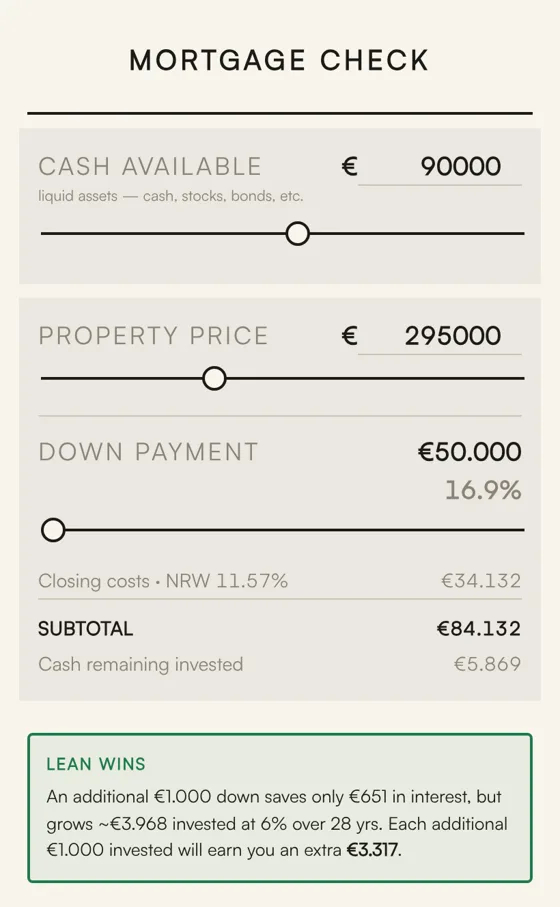
Each block is one line of the purchase: cash, price, down payment, rate and repayment, then a summary and a lifetime cost. The receipt format keeps it to one column on a phone, which is where the numbers get checked, usually in a viewing or at the bank. Drag the down payment beside the headline: at €56,000 the cash runs out; at €55,000 the verdict flips.
- Over budget
- Down payment plus closing costs exceeds the cash available. The receipt says by how much.
- Lean wins
- €1,000 more down saves less in interest than it would earn invested. Each extra €1,000 invested is worth the difference.
- Pay it down
- At high enough rates the interest saved wins, and a bigger down payment is the cheaper route.
Example: €295,000 flat in North Rhine-Westphalia, €90,000 cash, 4% interest, 2% Tilgung.
The levers
One notch on each lever, priced over the whole loan
The receipt moves each input by its smallest step and shows what it is worth.
Putting €1,000 more down saves €651 in interest. Leaving it invested grows it by €3,968. At German rates in this range, every extra euro of down payment beyond the minimum costs money.
The bigger lever is repayment speed. Raising the Tilgung by a tenth of a point saves €5,290, eight times what another €1,000 down does, for €20 a month.
Three markets
Same question, three sets of rules
Under the bonnet
One file, no server
One HTML file, no framework and no server. It installs to a phone’s home screen and remembers the last numbers entered on that phone. The German version sits at the root address; the UK and South African versions share a second address with a toggle.
- Format
- Single HTML page, installable web app
- Hosting
- Vercel, static
- Tax rules
- NRW Grunderwerbsteuer and fees; UK SDLT 2025/26; SARS transfer duty from April 2025
- Storage
- On the phone only, nothing sent anywhere
Every figure is an estimate. The rate is assumed fixed for the full term, there are no further contributions, and the market return is a flat assumption printed at the foot of the receipt.